Strategy Inc.
American software company, formerly MicroStrategy, that buys and holds bitcoin as its main treasury asset
American software company, formerly MicroStrategy, that buys and holds bitcoin as its main treasury asset

Strategy Inc., known until 2025 as MicroStrategy, is an American public company, founded in 1989 as a business software maker, that since 2020 has raised money to buy and hold bitcoin as its main treasury asset.
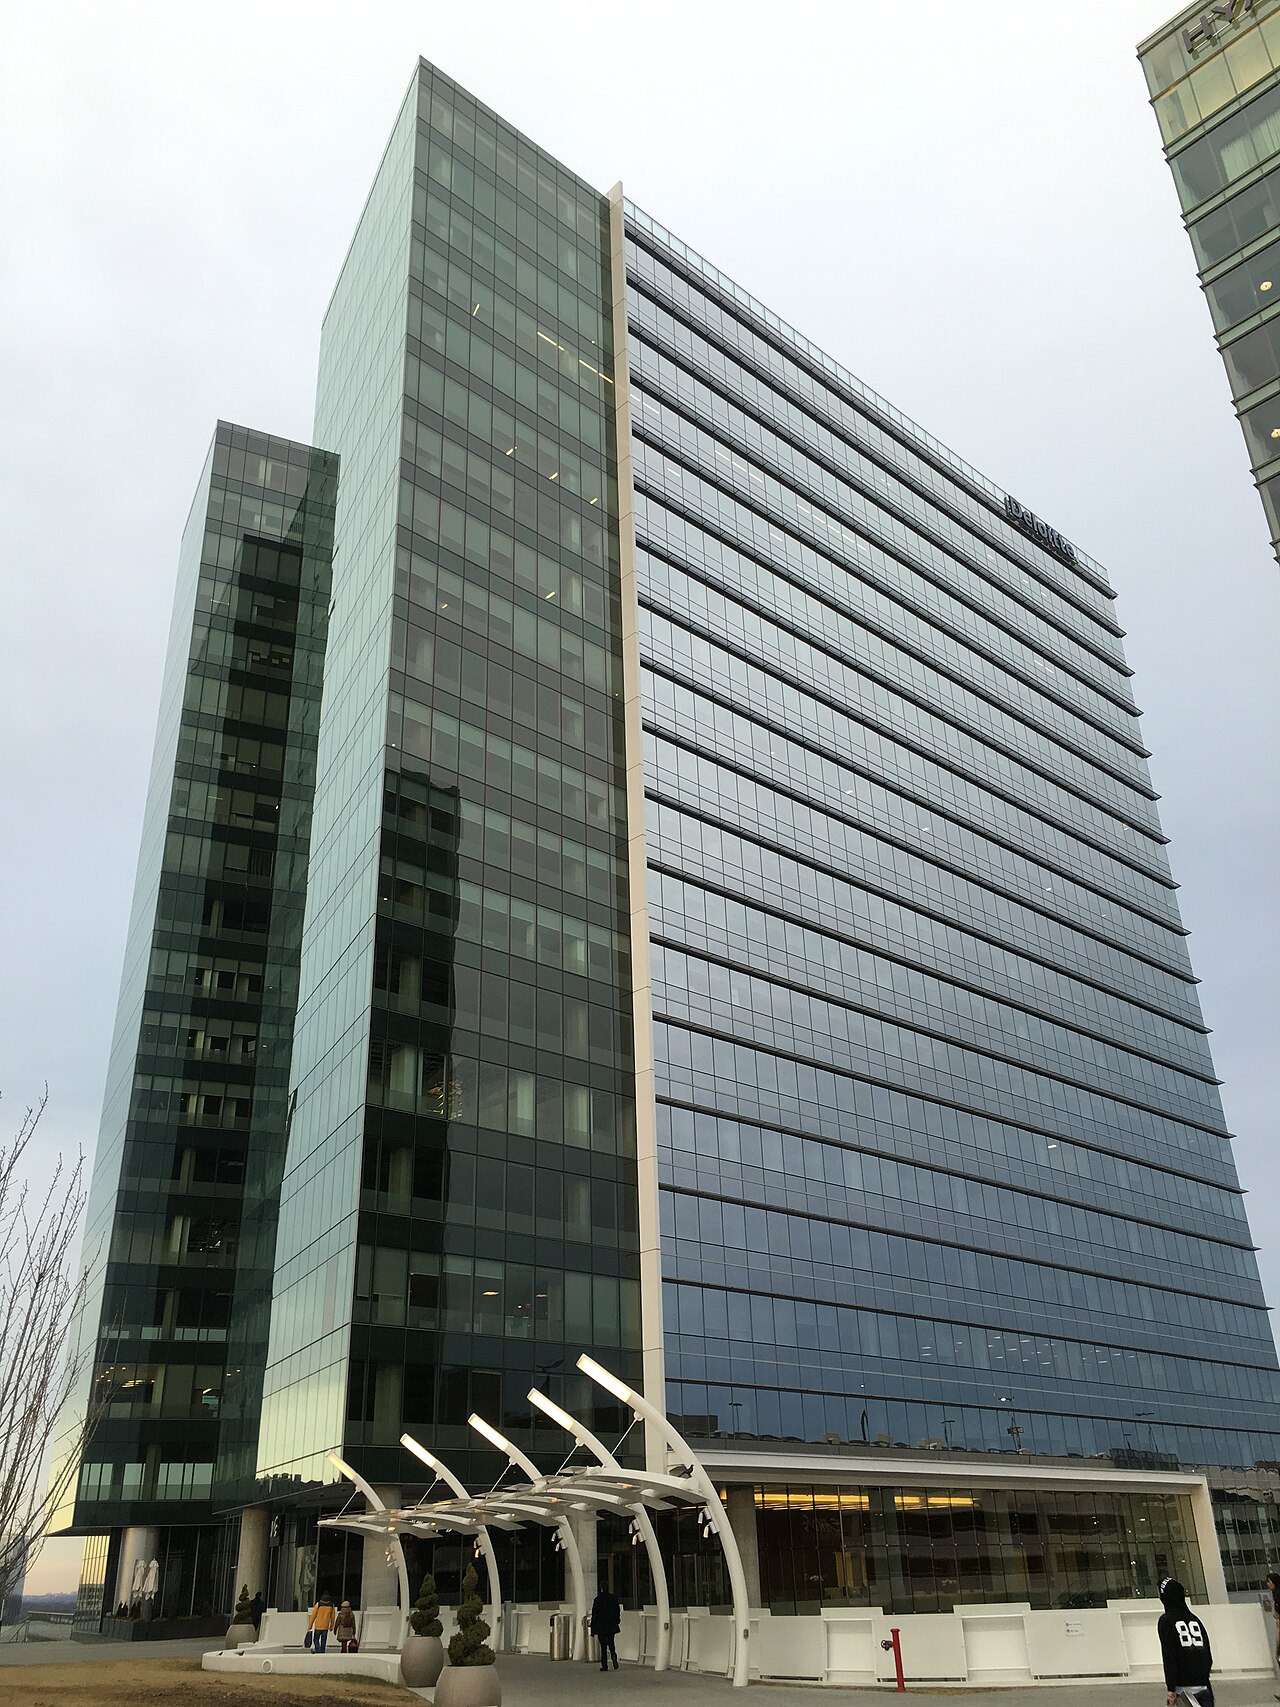
Via Wikimedia Commons: Tysons Tower Tysons VA 2016 02 07 01 by Justin.A.Wilcox, CC BY-SA 4.0.
Strategy is incorporated in Delaware and has its headquarters at 1850 Towers Crescent Plaza in Tysons Corner, Virginia, according to its annual report for 2025. It has two lines of activity. It describes itself as "the world's first and largest Bitcoin Treasury Company", raising money through shares and other securities to buy bitcoin, and it still sells enterprise analytics software (Strategy 10-K for 2025). Its class A common stock trades on the Nasdaq Global Select Market under the symbol MSTR. For the general model it pioneered, see Bitcoin treasury company; for the asset itself, see Bitcoin.
MicroStrategy was founded in November 1989 by Michael J. Saylor, who served as its president, chief executive and chairman from its founding, according to the company's annual report for 1998. The same report says its first business was software consulting, helping customers build custom decision support systems (software for querying and analysing large business databases), and that during 1994 and 1995 it turned increasingly to developing and selling its own software products, releasing a full set of them in 1995. By 1998 it called itself "a leading worldwide provider of enterprise DSS software" (MicroStrategy 10-K for 1998).
The company went public on 12 June 1998, selling 4,440,000 shares of class A common stock in an initial public offering underwritten by Merrill Lynch, Hambrecht & Quist and Friedman, Billings, Ramsey & Co. (MicroStrategy 10-K for 1998).
On 20 March 2000 MicroStrategy announced that, with the agreement of its auditors, PricewaterhouseCoopers, it would revise its results for 1998 and 1999, cutting its reported 1999 revenue from $205.3 million to between about $150 million and $155 million and turning a reported profit of $0.15 a share into a loss (MicroStrategy 8-K, 23 March 2000). The U.S. Securities and Exchange Commission later found that from the 1998 public offering until March 2000 the company had materially overstated its revenues and earnings, and should have reported net losses from 1997 onward. The restatement reduced revenue over three years by about $66 million of the $365 million reported, about 80 percent of it in 1999. The SEC traced the errors mainly to recognising revenue too early on deals that bundled software licences with services or future products that could not be separated from the sale (SEC order, 14 December 2000).
The share price fell by more than 60 percent on the day of the announcement, from $260 to close at $86, after a recent high of $333 (SEC order, 14 December 2000). On 14 December 2000 the company consented, without admitting or denying the findings, to a cease-and-desist order that imposed no fine but required governance changes and new controls over contracts and financial reporting (MicroStrategy 10-K for 2000). The same day the SEC filed a settled civil action against three officers, the two co-founders and the former chief financial officer, who without admitting or denying the allegations agreed to be enjoined from violating the antifraud and record-keeping provisions of the securities laws, to pay disgorgement totalling about $10 million, and to pay a civil penalty of $350,000 each (SEC Litigation Release No. 16829). In October 2000 the company entered into agreements to settle a shareholder class action and a derivative suit over the restatement (MicroStrategy 10-K for 2000).
On 11 August 2020 MicroStrategy, then describing itself as the largest independent publicly traded business intelligence company, announced that it had bought 21,454 bitcoins for $250 million, including fees. The purchase was one half of a capital allocation plan announced on 28 July 2020; the other half was a cash tender offer for up to $250 million of its own shares. In the announcement Saylor called bitcoin "a dependable store of value" with more long-term appreciation potential than holding cash (MicroStrategy press release, 11 August 2020).
In September 2020 the board adopted a Treasury Reserve Policy that made bitcoin "the primary treasury reserve asset on an ongoing basis", alongside cash beyond working needs, and in the first quarter of 2021 the company adopted a strategy of acquiring and holding bitcoin with the proceeds of capital raising as well (Strategy 10-K for 2025). The same report says that before 2025 the purchases were funded mainly by selling class A shares and senior convertible notes (debt that holders can exchange for shares), and earlier also from operating cash flow, senior secured notes and a term loan secured on bitcoin.
On 30 October 2024 the company announced what it called the "21/21 Plan": a goal of raising $42 billion over three years, $21 billion in equity and $21 billion in fixed-income securities, to buy more bitcoin. The announcement quoted Phong Le as president and chief executive (MicroStrategy press release, 30 October 2024); as of the 2025 annual report, Saylor was executive chairman and chairman of the board (Strategy 10-K for 2025).
By February 2025 the company was operating as "MicroStrategy Incorporated d/b/a Strategy", the name it used when it issued its Strike preferred stock on 5 February 2025 (8-K, 5 February 2025). On 11 August 2025 it amended its certificate of incorporation to change its legal name from "MicroStrategy Incorporated" to "Strategy Inc", with its securities keeping their Nasdaq symbols (8-K, 11 August 2025).
In 2025 the company issued five series of perpetual preferred stock, which it groups under the name "digital credit" (Strategy 10-K for 2025):
Strike was issued as 7,300,000 shares with a $100 liquidation preference (the amount holders are owed ahead of common shareholders if the company is wound up), cumulative dividends of 8 percent a year, payable quarterly when declared by the board, and a right to convert into class A shares at an initial price of $1,000 a share (8-K, 5 February 2025). In a liquidation the series rank, from highest to lowest, STRF, STRC, STRE, STRK and STRD, all behind the company's debt and ahead of its common stock (Strategy 10-K for 2025).
The company sells these securities and its class A shares gradually through "at-the-market" programmes, at prevailing market prices rather than in single offerings. Because bitcoin pays no interest or dividends, the annual report states that the company does not expect its software business to generate enough cash to cover its fixed obligations, and that it intends to fund preferred dividends mainly with the proceeds of selling class A shares. In December 2025 it set up a U.S. dollar reserve to support those dividends and interest payments; the reserve stood at $2.25 billion on 13 February 2026. As of 31 December 2025 its debt was about $8.25 billion, and at the time of the report S&P Global Ratings assigned it a corporate credit rating of B-, below investment grade (Strategy 10-K for 2025).
The company has two classes of common stock: class A shares carry one vote and class B shares ten. On 31 December 2025 the 19,640,250 class B shares held about 40.2 percent of the total voting power, which the annual report lists as a risk because it gives the holder of most of them, the executive chairman, significant influence over shareholder votes (Strategy 10-K for 2025).
The company reports its holdings in regular filings. As of 13 February 2026 it held about 717,131 bitcoins bought for an aggregate $54.5 billion, an average of about $76,027 each including fees (Strategy 10-K for 2025). As of 8 November 2026 it reported 850,364 bitcoins, bought for an aggregate $64.16 billion, an average of $75,456 each including fees (Strategy 8-K, 9 November 2026). The annual report notes that this concentration means any significant fall in the price of bitcoin affects the company's financial condition more than a diversified portfolio would (Strategy 10-K for 2025).
The analytics business continues. The 2025 annual report describes Strategy One, a cloud-based platform for business intelligence, reporting and embedded analytics, and Strategy Mosaic, a "universal data layer" meant to give organisations consistent definitions across their data sources. Total revenue was $477.2 million in 2025, against $463.5 million in 2024 and $496.3 million in 2023, and international revenue accounted for 43.0 percent of the total in 2025 (Strategy 10-K for 2025).
From 1 January 2025 the company adopted Accounting Standards Update 2023-08, which requires its bitcoin to be measured at fair value, with gains and losses from changes in that value recognised in net income each reporting period (Strategy 10-K for 2025). Its results therefore move with the bitcoin price: it reported a net loss of about $3.85 billion for 2025 and $1.17 billion for 2024, after net income of about $429 million in 2023 (Strategy 10-K for 2025).
Strategy is widely treated as the model for companies that followed it. In a December 2025 note for the consultancy Brattle, Sujay Dave and Anil Donmez describe it as "often cited as the pioneer and archetype" of digital asset treasury companies, and cite research putting its shares at a 53 percent premium to the value of its net assets in August 2025, meaning investors paid more for the shares than the underlying holdings were worth. They also give it as an example of a large company whose quarterly reports explicitly describe how crypto price volatility, custody and borrowing affect its finances, in a sector where they found such disclosure uneven (Dave and Donmez, 2025).
The company's own risk disclosures list, among others, its dependence on capital markets to fund its obligations, the possibility of having to sell bitcoin below cost if its dollar reserve were exhausted and financing were unavailable, the risk of loss at custodians, and the influence of its controlling class B shareholder (Strategy 10-K for 2025).
 Get Micwyn on your home screenIts own icon, full screen, and notifications.