Version 3 (current)
Nov 16, 2026. Version history
A bid-ask spread is the gap between the highest price a buyer is bidding for a security and the lowest price a seller is asking for it at the same moment. It is one of the costs of trading, and a common measure of how easily a security can be bought or sold.
In the United States the stock-market rules state the spread as the difference between the national best offer and the national best bid, the best prices for the stock as calculated and disseminated for the whole U.S. market.[1] Randi Næs and Johannes Skjeltorp, researchers at Norges Bank, Norway's central bank, writing in its bulletin in 2006, describe it in the same terms: the difference between the best bid and the best ask is the spread, and a dealer who stands ready to buy and sell earns that difference in return for providing liquidity.[2] The ask is also called the offer, so the same measure is sometimes called the bid-offer spread.
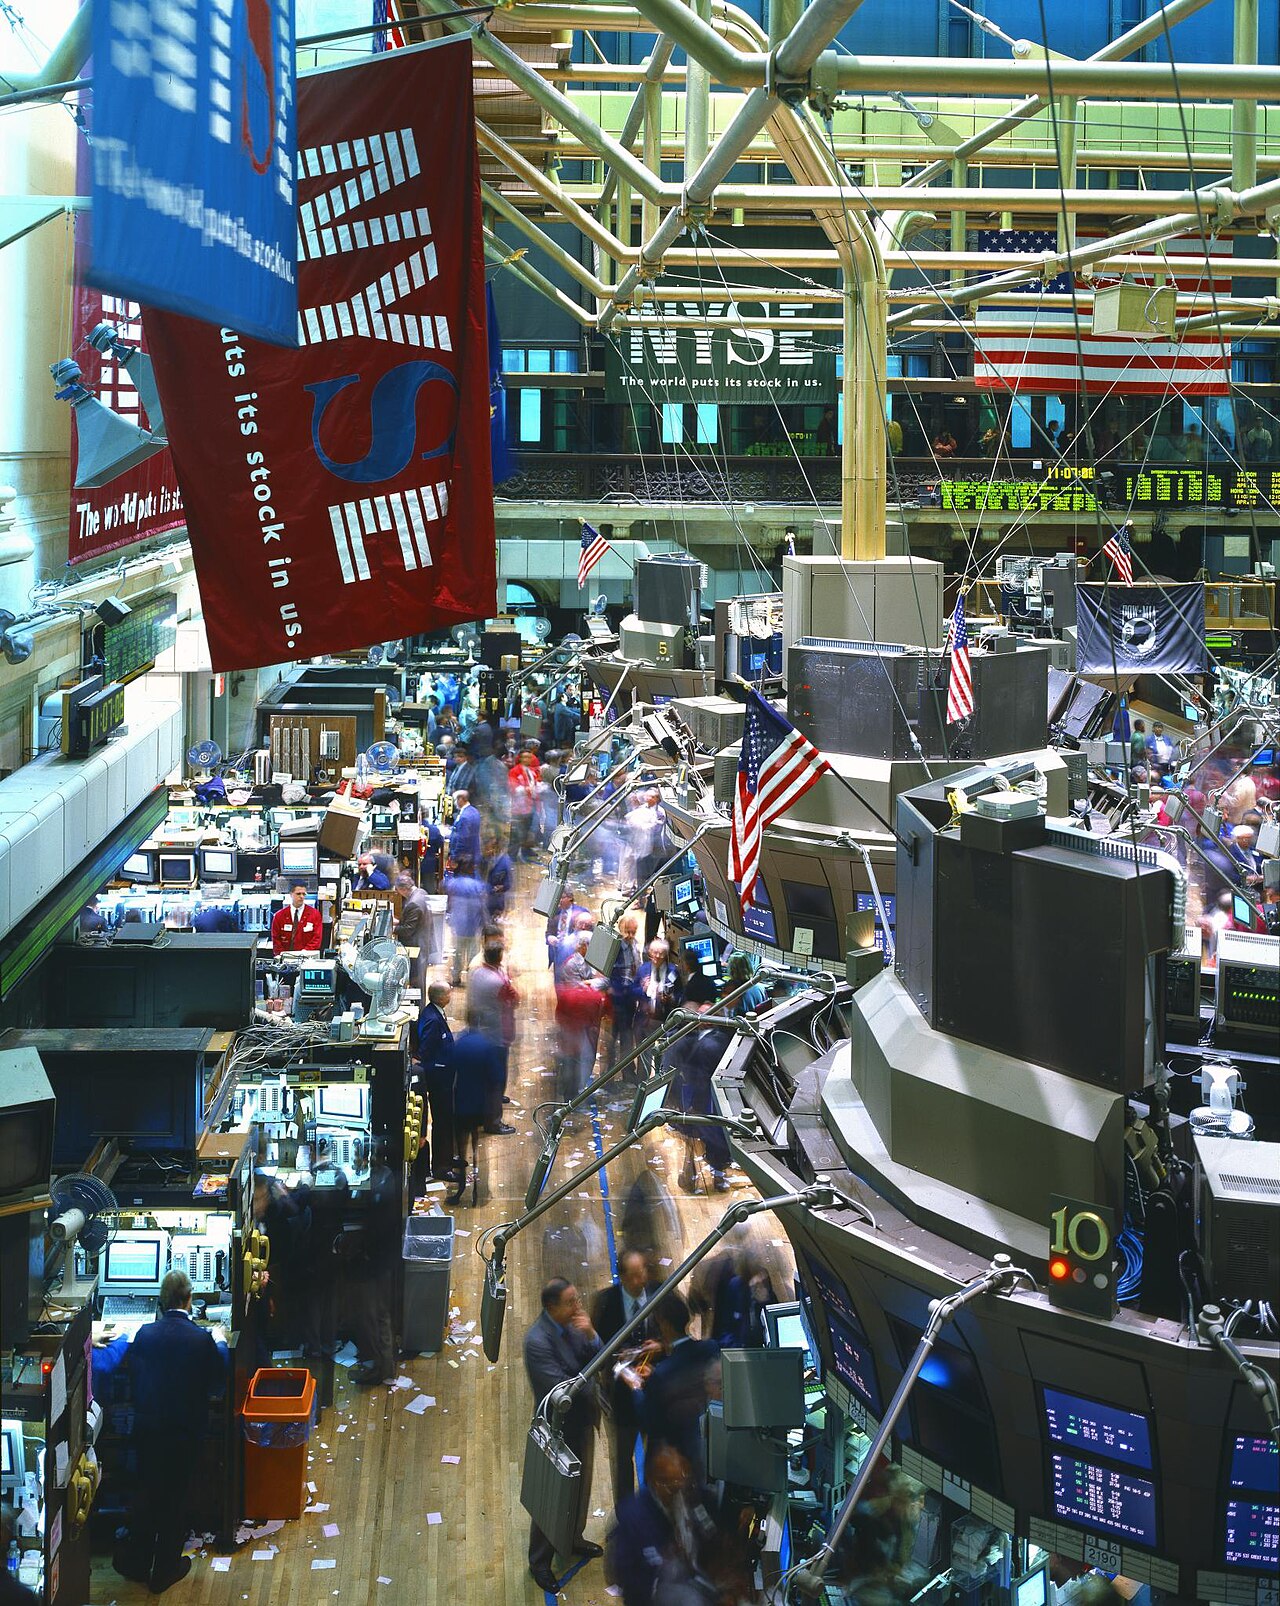
Via Wikimedia Commons: No Known Restrictions Trading Floor, New York Stock Exchange (Highsmit by Carol M. Highsmith, public domain.
Bid, ask and midpoint
A spread arises wherever prices are quoted on both sides. In a dealer market, intermediaries called dealers or market makers post the prices at which they will buy and sell, and trade with investors at those prices. In a limit order market, investors themselves post orders to buy or sell at stated prices in an order book, and a trade happens when a buy order and a sell order meet; the spread is then the gap between the best buy order and the best sell order waiting in the book.[2] Some markets, called hybrid markets, combine the two; Næs and Skjeltorp give the New York Stock Exchange as an example.[2]
The price halfway between the bid and the ask is called the midpoint. In the models economists use, the midpoint is often treated as the security's equilibrium price, and the bid and ask sit below and above it.[2] An investor who buys at the ask pays a little more than the midpoint, and one who sells at the bid receives a little less.
Spreads are compared across securities as a percentage. The relative spread is the difference between the highest bid and the lowest ask divided by the average of the two, which is the midpoint.[2] For example, with a bid of $49.98 and an ask of $50.02, the spread is $0.04, the midpoint is $50.00, and the relative spread is 0.04 ÷ 50.00 = 0.08 percent, or 8 basis points (a basis point is one hundredth of a percent). Someone who bought at the ask and sold straight back at the bid, with no change in the quotes, would lose that $0.04 a share.
Why spreads exist
Waiting and immediacy
The economist Harold Demsetz analysed the spread in "The Cost of Transacting", published in the Quarterly Journal of Economics in 1968, which has a section on the determination of what he called the ask-bid spread.[3] As Næs and Skjeltorp summarise his argument, Demsetz pointed out that trading carries an indirect cost besides fees and commissions: because buyers and sellers do not arrive at the same time, an investor who wants to buy at once must pay a higher price to persuade a patient seller to sell, and the same holds in reverse for a hurried seller. The price at which a trade happens therefore depends on whether the trader wants to trade quickly, so that there are two equilibrium prices rather than one.[2]
Inventory and order-processing costs
The first formal models of spreads looked at the dealer. In a 1976 model by Garman, a dealer who sets prices to stay in business without running out of shares finds it best to set different bid and ask prices, which explains why a dealer market has a positive spread.[2] Amihud and Mendelson extended this in 1980 to a dealer who adjusts prices over time to keep an inventory near a target level, lowering both the bid and the ask as inventory grows and raising them as it shrinks, a behaviour known as quote shading.[2] In these models the dealer sets the bid and ask so as to cover the costs of processing orders and of holding an inventory.[2]
Information
A second family of models starts from the observation, credited to a 1971 article by Bagehot, that some traders know more than others.[2] A dealer must trade at the prices posted, while an informed trader trades only when it pays, so the dealer loses on trades with better-informed investors. Copeland and Galai showed in 1983 that a dealer who cannot tell informed from uninformed traders will set a positive spread to cover the expected loss, and Glosten and Milgrom showed in 1985 how a dealer learns from the flow of orders, so that private information works its way into prices over time.[2]
Taken together, the early literature divides the spread into a component that compensates for the risk of trading with a better-informed investor and a component that covers inventory and order-processing costs.[2] Later models added the case where liquidity providers have market power, in which they can earn what economists call oligopoly rents, profits above what full competition would allow.[2]
Measuring the spread
Quoted, effective and realized spreads
The spread posted on screens is the quoted spread. Many trades, however, happen inside the quotes, at prices better than the best bid or ask, so researchers and regulators also measure the effective spread, which looks at the price actually paid. Under the U.S. rules for reporting execution quality, the effective spread for a buy order is double the difference between the execution price and the midpoint at the time the order was received, and for a sell order double the difference between the midpoint and the execution price.[1] Doubling puts it on the same scale as the quoted spread. A buy order is executed with price improvement when it is filled below the national best offer, and a sell order when it is filled above the national best bid.[1]
Continuing the example above, a buy order filled at $50.01 when the midpoint was $50.00 has an effective spread of 2 × $0.01 = $0.02, half the quoted spread of $0.04. The ratio of effective to quoted spread is then 50 percent; a ratio below 100 percent means the order was filled inside the quotes.
The realized spread is calculated the same way but uses the midpoint at a set interval after the trade instead of the midpoint when the order arrived.[1]
Roll's estimate from prices alone
Quote data are not always available, especially for older periods. In 1984 the economist Richard Roll published a way to infer the effective spread from a series of trade prices alone, in "A Simple Implicit Measure of the Effective Bid-Ask Spread in an Efficient Market" in the Journal of Finance.[4] His reasoning was that in an efficient market the underlying value moves randomly, but trades that bounce between the bid and the ask make successive price changes tend to reverse.[4] He showed that, under his assumptions, the covariance between one price change and the next equals minus the square of half the spread, which gives the estimate: spread = 2√(−cov), where cov is the first-order serial covariance of price changes.[4]
Roll tested the measure on daily and weekly returns for stocks listed on the New York and American stock exchanges from 1963 to 1982 and found a strong negative relation between the estimated spread and company size, measured as share price times shares outstanding, the figure better known as market capitalization.[4] Larger companies, in other words, showed smaller estimated spreads. He also found that spreads estimated from weekly data were on average about six times as large as those from daily data.[4]
Spreads and the cost of trading
Studies of trading costs separate explicit costs, chiefly brokers' commissions, from implicit ones. In the division used by Keim and Madhavan in 1998, implicit costs include the spread, the effect a trade has on the price, and the cost of not trading at the time wanted.[2] Estimating these costs is difficult, because the components are hard to separate and a single recorded trade is often only part of a larger order.[2]
Whether spreads also affect long-run returns is debated. Amihud and Mendelson, in a 1986 study of New York Stock Exchange stocks from 1961 to 1980, found that expected return rose with the relative spread, though at a declining rate, and explained this with a model in which investors with long horizons hold the stocks with the widest spreads in return for higher returns; in their view the spread acts as a kind of tax that some investors avoid and others accept for compensation.[2] Later studies of the link between spread and return have reached mixed results, some finding it and others not.[2]
Via Wikimedia Commons: Nasdaq MarketSite (51494550508) by ajaysuresh, CC BY 2.0.
The Nasdaq odd-eighths study
Until 2001 American stock quotes moved in fractions of a dollar.[6] In 1994 William Christie and Paul Schultz reported in the Journal of Finance that on Nasdaq, a market built on competing dealers that was meant to produce narrow spreads, quotes at odd eighths of a dollar (1/8, 3/8, 5/8, 7/8) were almost absent for 70 of 100 actively traded stocks, including Apple Computer and Lotus Development.[5] They found that the pattern could not be explained by trading activity or other factors thought to affect spreads, and that it implied an inside spread of at least $0.25 for many Nasdaq stocks, raising the question of whether Nasdaq dealers were implicitly colluding to keep spreads wide.[5] According to Næs and Skjeltorp, this work and a companion study published the same year led to the revelation of price-fixing by Nasdaq dealers.[2]
Decimal prices
U.S. stock markets completed the move from fractional to decimal prices on 9 April 2001, when the smallest step in which a stock could be quoted fell from one sixteenth of a dollar to one cent.[6] In a speech that July, Laura Unger, then Acting Chairman of the Securities and Exchange Commission, reported that Nasdaq found the average effective spread for its securities had shrunk about 50 percent, and that the SEC's Office of Economic Analysis estimated a fall of about 28 percent for New York Stock Exchange securities.[6]
Narrower spreads came with smaller quotes. The same speech reported that quote sizes, the number of shares offered at the quoted prices, had fallen by about 60 percent for NYSE-listed stocks and by about 68 percent in preliminary analyses of Nasdaq securities.[6]
Tick size and the minimum spread
The smallest step in which a price can be quoted, the tick size, sets a floor under the spread: a stock quoted in whole cents cannot have a spread narrower than one cent. In U.S. stock markets that step fell to one cent in 2001 (see "Decimal prices" above).[6] It is set by Rule 612 of Regulation NMS, the rule on minimum pricing increments.[9]
On 18 September 2024 the Securities and Exchange Commission adopted an amendment to Rule 612 that creates a smaller step, $0.005, for bids, offers and orders priced at $1.00 or more in certain stocks.[9][10] The stocks are those whose time-weighted average quoted spread, the quoted spread averaged over time during an evaluation period, is $0.015 or less.[9] The Commission's reasoning was that stocks with sufficiently narrow spreads would trade better with a finer step. In the adopting release it estimated that up to 74.3 percent of the share volume traded in U.S. national market system stocks in 2023 may have had spreads constrained by the existing minimum increments.[9] The adopted rule is narrower than the proposal, which had also included steps of $0.002 and $0.001, and it sets no minimum increment for trades themselves.[9]
The change has not yet taken effect. On 31 October 2025 the Commission granted temporary exemptive relief from the compliance date until the first business day of November 2026, and on 11 June 2026 it extended that relief to the first business day of November 2027.[10] As of November 2026, therefore, the new step is not yet required.
Disclosure of execution quality
The Securities and Exchange Commission adopted Rule 605 of Regulation NMS in 2000 to help the public compare and evaluate execution quality at different market centers through standardized monthly reports.[7][8] On 6 March 2024 the Commission adopted amendments that extend the reports to broker-dealers that introduce or carry 100,000 or more customer accounts and to single-dealer platforms.[7][8]
The amendments added new measures, among them the average effective spread divided by the average quoted spread, which the SEC describes as a percentage-based measure of how much price improvement an order received, along with percentage-based effective and realized spreads and realized spreads at time horizons from less than 100 microseconds to five minutes.[8] Every entity subject to the rule must also make public a summary report in CSV and PDF formats.[8] These reports allow the effective-to-quoted ratio described above to be compared across brokers for the same kinds of orders.
Sources
- "17 CFR § 242.600 – NMS security designation and definitions", Code of Federal Regulations, via Legal Information Institute, Cornell Law School, accessed 12 November 2026. law.cornell.edu/cfr/text/17/242.600
- Randi Næs and Johannes Skjeltorp, "Is the market microstructure of stock markets important?", Economic Bulletin 3/06 (vol. 77), pp. 123–132, Norges Bank, 2006. norges-bank.no/globalassets/upload/english/publications/economic-bu…
- Harold Demsetz, "The Cost of Transacting", Quarterly Journal of Economics, vol. 82, no. 1, pp. 33–53, 1968 (EconPapers record). econpapers.repec.org/article/oupqjecon/v_3a82_3ay_3a1968_3ai_3a1_3a…
- Richard Roll, "A Simple Implicit Measure of the Effective Bid-Ask Spread in an Efficient Market", Journal of Finance, vol. 39, no. 4, pp. 1127–1139, September 1984. doi.org/10.2307/2327617
- William G. Christie and Paul H. Schultz, "Why Do NASDAQ Market Makers Avoid Odd-Eighth Quotes?", Journal of Finance, vol. 49, no. 5, pp. 1813–1840, 1994 (IDEAS/RePEc record with abstract). ideas.repec.org/a/bla/jfinan/v49y1994i5p1813-40.html
- Laura S. Unger, Acting Chairman, U.S. Securities and Exchange Commission, "New Millennium, New Market", speech before the Exchequer Club, Washington, D.C., 18 July 2001. sec.gov/news/speech/spch509.htm
- "SEC Adopts Amendments to Enhance Disclosure of Order Execution Information", U.S. Securities and Exchange Commission press release 2024-32, 6 March 2024. sec.gov/news/press-release/2024-32
- "Fact Sheet: Disclosure of Order Execution Information" (Release No. 34-99679), U.S. Securities and Exchange Commission, March 2024. sec.gov/files/34-99679-fact-sheet.pdf
- "Regulation NMS: Minimum Pricing Increments, Access Fees, and Transparency of Better Priced Orders", final rule, Release No. 34-101070, Federal Register vol. 89, no. 195, 8 October 2024, pp. 81620 ff. govinfo.gov/content/pkg/FR-2024-10-08/html/2024-21867.htm
- U.S. Securities and Exchange Commission, "Order Granting Temporary Exemptive Relief ... from Compliance with Rule 600(b)(89)(i)(F), Rule 610(c) and Rule 612 of Regulation NMS, as Amended", Release No. 34-105656, 11 June 2026. sec.gov/files/rules/exorders/2026/34-105656.pdf
