Index fund
An investment fund that tracks a market index by holding the securities in it, in proportion
📖 Dictionary: index fund · 📚 Library
An investment fund that tracks a market index by holding the securities in it, in proportion
📖 Dictionary: index fund · 📚 Library

An index fund is an investment fund that aims to match the performance of a market index, such as the S&P 500, by holding the securities in that index, or a representative sample of them, in roughly the same proportions.[1]
The Investment Company Institute (ICI), the trade association of American investment funds, describes index funds as designed to track the performance of a market index: the manager buys all the securities in the index or a representative sample of them, so that the fund's value moves with the index.[1] Market indexes are rules-based benchmarks whose providers publish their methods in detail.[3] Micwyn's entry Stock market index explains how they are built. Index investing is often called passive investing, in contrast to active management, in which a manager picks securities or times the market in an attempt to beat a benchmark.[2] Index funds come in two main forms: index mutual funds, the traditional form, and exchange-traded funds (ETFs), whose shares can be traded during the day on an exchange.[2]
A passive strategy is usually carried out by holding each of the index's constituent securities in line with its weight in the index, according to a 2018 special feature in the BIS Quarterly Review, published by the Bank for International Settlements.[2] Once the portfolio matches the index, it needs no trading unless the index itself changes or money flows into or out of the fund.[2] Vanguard describes its index funds as holding the same securities as their benchmarks or representative samples of them, targeting the indexes' weights and rebalancing when the indexes do.[3]
Indexes are typically weighted by market value (each company's share price multiplied by its shares), so a fund tracking one holds more of large companies than of small ones.[2] Vanguard points out a consequence: a company that is 2% of the market before an index fund buys it is still 2% of the market afterwards, since the fund buys in proportion to existing market values.[3]
A fund's costs make it trail its index slightly. Vanguard reports that the original share class of its S&P 500 fund returned 11.44% a year on average from its 1976 launch to 31 March 2026, against 11.68% a year for the S&P 500 itself, a shortfall of 0.24 percentage points a year.[3]
With little overhead and trading, index funds cost less to manage than actively managed funds, as Vanguard puts it.[3] The ICI calls this way of managing a portfolio the primary reason that index funds tend to have below-average expense ratios, the expense ratio being a fund's annual operating costs as a share of its assets.[1] Vanguard, citing Morningstar data, gives asset-weighted average expense ratios at the end of 2024 of 0.11% for index funds and 0.59% for actively managed funds in the United States.[3] Its own S&P 500 fund charged 0.43% a year when it began; as of 2026 its largest share classes charge 0.03% and 0.04%.[3]
The arithmetic of costs is the core of the case for index funds. The BIS article, citing the economist William Sharpe (1991) among others, calls beating the market a "zero sum game" and summarises the reasoning: since passive investors earn the market return before costs, the average return across all active investors must also equal the market return, and after their higher trading costs and fees active investors on average earn less.[2]
The intellectual groundwork came from academic finance. The BIS article traces the rationale for passive investing to the theory of efficient markets, which holds that security prices quickly absorb available information, so that future excess returns cannot be predicted.[2] In his 1973 book A Random Walk Down Wall Street, the Princeton economist Burton Malkiel called for a no-load, minimum-management-fee mutual fund that would simply buy the stocks in the market averages.[3] The financial journalist Jason Zweig, writing in The Wall Street Journal on the fund's 40th anniversary, notes that the analyst Benjamin Graham had argued for something like an index fund at least as early as 1963, and that the MIT economist Paul Samuelson's 1974 article "Challenge to Judgment" argued that choosing superior stock pickers was futile.[4] Samuelson wrote that the evidence led him to think "most portfolio managers should go out of business".[4]
The first indexed portfolios were run for pension funds rather than the public. In 1971 a division of Wells Fargo started a $6 million indexed portfolio for the pension fund of Samsonite, the luggage maker, holding equal amounts of major New York Stock Exchange companies.[4] Equal weighting required frequent trading, and the managers soon switched to holding stocks in proportion to their size.[4] By June 1975 American National Bank in Chicago was running about $300 million in several index funds for institutional clients.[4]
John C. Bogle had argued in his 1951 Princeton undergraduate thesis that costs were a drag on the returns of the mutual fund industry.[3] In 1974, after being dismissed from Wellington Management, he became head of a new company, Vanguard, set up to administer the Wellington funds and owned by the funds themselves, and so by their shareholders.[5] On 31 August 1976 Vanguard launched First Index Investment Trust, which tracked the S&P 500 and was the first index fund offered to individual investors.[3][5] Bogle had hoped to raise $50 million to $150 million; the offering raised about $11.3 million, too little to buy all 500 stocks, so the fund started with 280 of them.[3][5] Bogle later called the result "an abject failure", and critics called it "Bogle's Folly".[3] For about its first six months the fund was sold through brokers with a sales charge; in early 1977 Vanguard dropped such charges for all its funds.[3] The fund was later renamed Vanguard 500 Index Fund.[3]
Growth was slow at first. According to Zweig, index funds held $511 million in 1985, $55 billion in 1995 and $868 billion in 2005.[4] Vanguard launched the first bond index fund in 1986.[3] The same year, the Federal Employees' Retirement System Act set up the Thrift Savings Plan for U.S. federal workers as an index-based plan.[3]
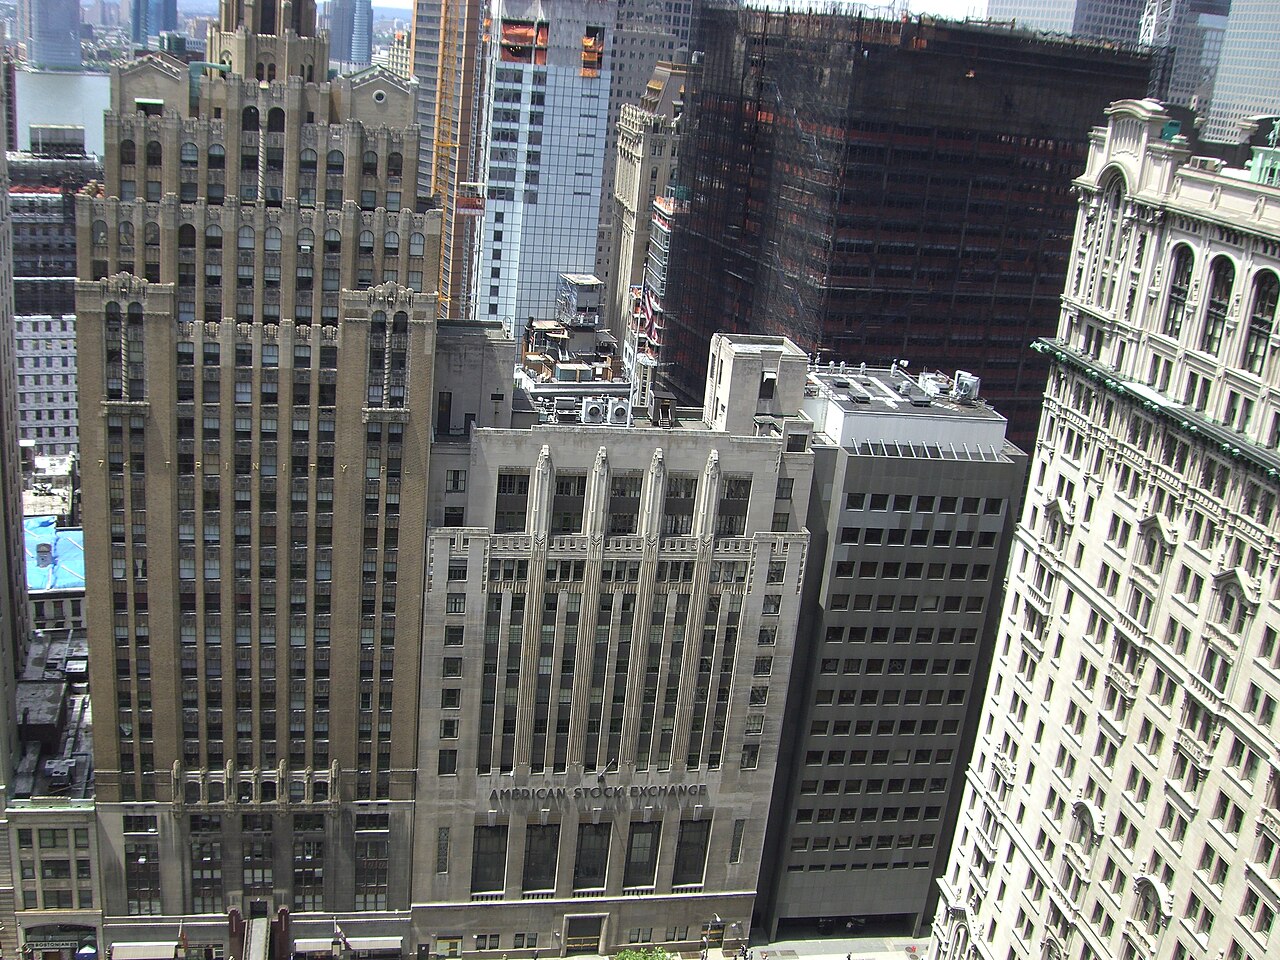
Via Wikimedia Commons: Old American Stock Exchange Building 2009 by Sebaso, CC BY-SA 4.0.
The exchange-traded index fund came next. In January 1993 State Street and the American Stock Exchange launched an S&P 500 fund known by its ticker, SPY, after a three-year collaboration; State Street calls it the first US-listed ETF.[6] Its shares trade on an exchange like a stock; at launch, State Street received the 500 stocks from a broker-dealer and delivered fund shares in return, which the broker-dealer could then sell on the exchange.[6] The BIS notes that ETFs grew even faster than index mutual funds in the decade to 2017, and that their share of passive fund assets passed 40% in June 2017.[2]
By the end of 2025, index mutual funds and index ETFs in the United States held $19.1 trillion, 52% of the assets of long-term funds (funds other than money market funds), up from 19% at the end of 2010.[1] Index funds that invest in American stocks held 19% of the value of the U.S. stock market at year-end 2025, while actively managed stock funds held 11% and other investors, such as pension funds, insurers, hedge funds and individuals, held 69%, according to the same source.[1] The ICI reports that actively managed U.S. stock mutual funds had net outflows in every year after 2005, while index stock funds generally had inflows.[1]
Worldwide, the BIS estimated that passive funds managed about $8 trillion, or 20% of all investment fund assets, in June 2017, up from 8% a decade earlier.[2] Index funds are also built into retirement saving: Vanguard reports that 96% of U.S. defined-contribution retirement plans offered target-date funds at the end of 2024, funds that use index funds as a core building block.[3]
S&P Dow Jones Indices publishes a regular comparison of active funds with their benchmark indexes, the SPIVA U.S. Scorecard. Its mid-year 2025 edition found that, measured to 30 June 2025, 88.29% of actively managed large-company U.S. stock funds had trailed the S&P 500 over 15 years and 91.03% over 20 years.[7] Over the first half of 2025 alone, the figure was 54%.[7] The scorecard counts funds that were merged or closed along the way, which matters because only 34.70% of the large-company funds in the 20-year sample survived the whole period.[7] The BIS article reports that the academic literature reaches a similar conclusion: after fees and expenses, the average active stock fund has underperformed the market over long horizons, and funds that outperform in one period seldom keep doing so.[2]
The case for active management has not disappeared. The BIS article sets out two arguments for it: informed active managers can earn above-market returns at the expense of less-informed active investors, and because index funds must trade when their indexes change, active investors can profit by anticipating those predictable trades.[2]
Index funds rely on the trading of active investors to set prices; the BIS describes passive managers as free-riding on that work.[2] If passive investing grew large enough, prices might carry less information about individual companies, and capital could be misallocated.[2] Index funds buy and sell all the stocks in an index together as money flows in and out, which can make those stocks move more closely together.[2] Studies cited by the BIS find that stocks added to the S&P 500 become more correlated with the index and see trading volume rise and bid-ask spreads narrow.[2] The authors also point to counterweights: mispricing would raise the rewards for active analysis, and, as of 2018, passive funds held only a modest share of most securities markets.[2]
Because index funds follow their indexes mechanically, a decision by an index provider can move large sums. The BIS gives the example of MSCI's reclassification of Israel from an emerging to a developed market in 2010, which was followed by about $2 billion of net equity fund outflows from Israel in the month the change took effect, because Israel's weight in the developed-market index was smaller than its earlier weight in the emerging-market index.[2] For bond index funds, the BIS notes that index weights rise with the amount of debt an issuer has outstanding, so growth in such funds channels demand toward the largest, and potentially more indebted, issuers.[2]
Most index fund assets are managed by a few firms. The ICI reports that the ten largest fund companies, which manage most index mutual fund assets, held 72% of all U.S. mutual fund and ETF assets at year-end 2025, up from 46% in 2005.[1] A 2017 study in Business and Politics by Jan Fichtner, Eelke Heemskerk and Javier Garcia-Bernardo found that BlackRock, Vanguard and State Street, which it called the "Big Three", together were the largest shareholder in about 88% of S&P 500 companies, and that they generally vote with management, except in director elections.[8]
The legal scholars Lucian Bebchuk and Scott Hirst argue in the Columbia Law Review that index fund managers have strong incentives to underinvest in stewardship, meaning the monitoring of and voting on the companies they own, and to defer too much to corporate managers.[9] Jill Fisch, Assaf Hamdani and Steven Davidoff Solomon take a different view: they argue that competition for investors' money gives fund sponsors reasons to engage with the companies they hold, and that many existing critiques are unfounded, while agreeing that passive investing raises new concerns about concentrated ownership, conflicts of interest and common ownership (the same investors owning large stakes in competing firms).[10] The BIS article adds that, unlike active investors, index funds cannot sell a company's shares to signal disapproval, which could weaken market discipline on issuers.[2]
Whether index funds steady or amplify market swings depends mostly on how their end investors behave.[2] The BIS found that in recent periods of stress, investors in index mutual funds behaved more steadily than investors in active mutual funds, which saw persistent outflows, while flows into and out of ETFs were relatively volatile.[2]
 Get Micwyn on your home screenIts own icon, full screen, and notifications.