A bond is a debt security: an investor lends money to a government, company or other body for a set time, and the issuer promises to pay interest along the way and to repay the amount borrowed when the bond matures.
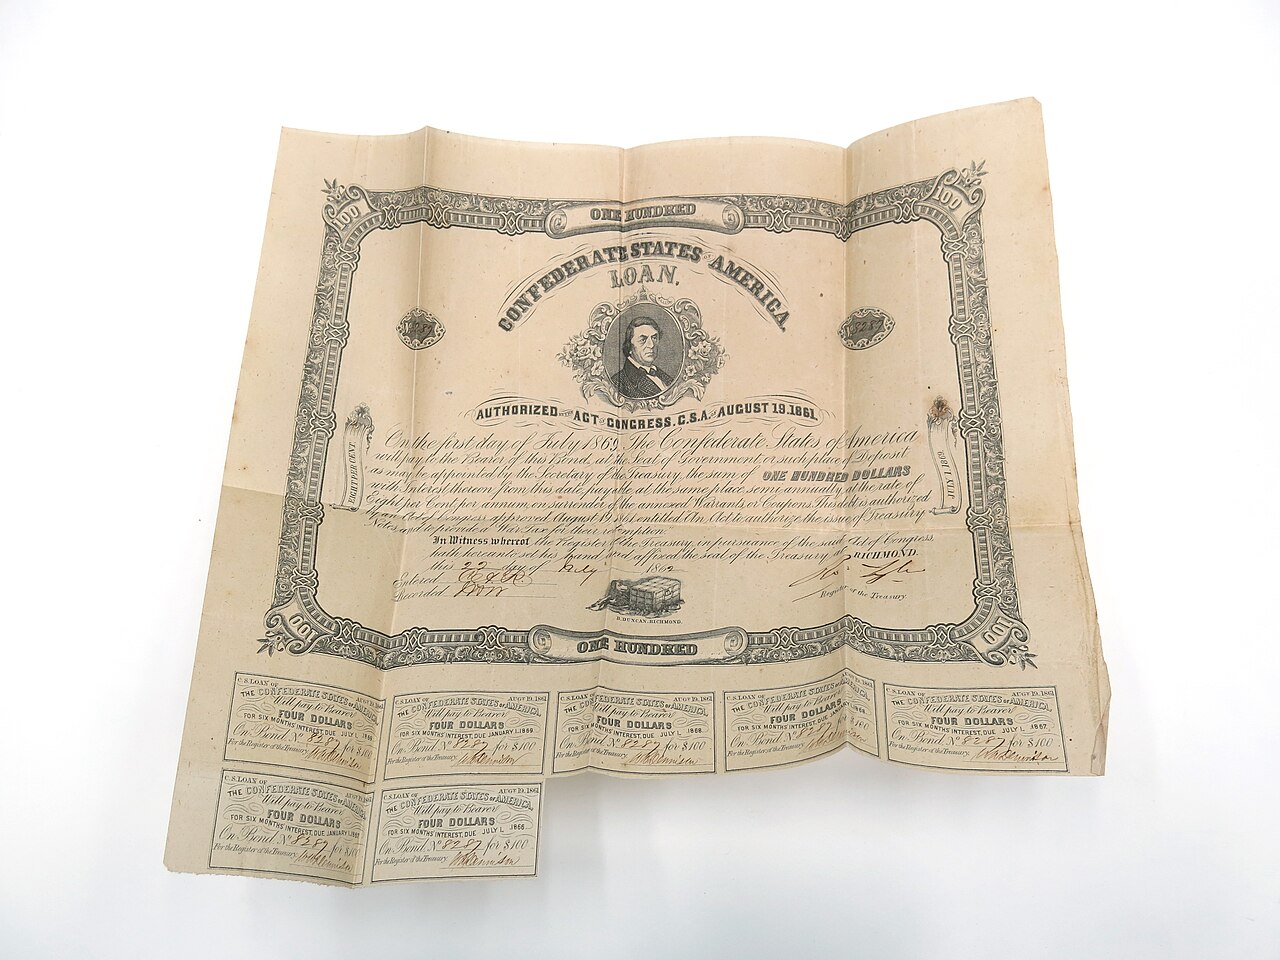
A Confederate States of America loan certificate for 100 dollars, with interest coupons attached at the bottom.
The U.S. Securities and Exchange Commission (SEC) describes a bond as a debt security, like an IOU: a buyer of a bond is lending to the issuer, which may be a government, a municipality or a corporation, and the issuer promises a specified rate of interest during the life of the bond and repayment of the principal when it comes due. Because most bonds provide fixed interest payments until the bond matures, they are also called fixed-income securities. This entry explains how bonds work, chiefly using United States examples, where most of its sources come from.
Basic terms
A bond is described by a few numbers fixed when it is issued:
Face value (par value): the principal that the issuer repays at the end. The SEC uses principal, face value and par value for the same amount.
Coupon: the interest the bond pays, stated as a percentage of face value. The Financial Industry Regulatory Authority (FINRA) gives the example of a bond with a par value of $1,000 and an annual interest rate of 4.5 percent, which pays $45 a year; if it pays semiannually, the holder receives $22.50 twice a year.
The SEC lists three reasons investors buy them: they provide a predictable income stream, usually with interest paid on a regular schedule such as every six months; a bond held to maturity returns its whole principal, so bonds are a way to preserve capital; and they can help offset the swings of stock holdings.
A bondholder is a lender, not an owner. FINRA points out that the buyer of a corporate bond receives the equivalent of an IOU from the issuer and no ownership rights in the company, but is more likely than common stockholders to recover some of the investment if the company goes bankrupt.
Corporate bonds, issued by private and public companies. Investment-grade corporate bonds carry higher credit ratings and less credit risk; high-yield bonds carry lower ratings and pay higher interest in return for the greater risk.
Municipal bonds ("munis"), issued by states, cities, counties and other government bodies. General obligation bonds are paid from an issuer's general fund or specific taxes, often property taxes; revenue bonds are instead backed by revenues from a specific project or source, such as highway tolls or lease fees. The SEC notes that interest on municipal bonds is generally exempt from federal income tax.
U.S. Treasury securities, issued by the Department of the Treasury, which carry the full faith and credit of the U.S. government. By maturity they are bills (up to 52 weeks), notes and bonds. The Treasury itself sells Treasury bonds for a term of either 20 or 30 years; they pay a fixed rate of interest every six months, set at auction, and can be bought in units of $100. Treasury Inflation-Protected Securities (TIPS) have principal that is adjusted with the Consumer Price Index.
A bond's face value and coupon stay fixed for its life, but once it has been issued it can be resold, and its price then moves with the market. FINRA explains that bond prices are quoted as a percentage of par: a $1,000 bond trading at par is said to be trading at 100, one quoted at 105 is trading at a premium for $1,050, and one at 95 at a discount for $950.
The yield is the return a buyer earns at a given price, and it moves inversely to the price. A worked illustration, calculated for this entry, shows the size of the effect. Take a bond with a face value of $1,000, a 4 percent coupon paid as $20 every six months, and ten years left to run. Its price is the present value of those 20 coupon payments and the final $1,000, discounted at the rate buyers now demand:
If buyers demand 4 percent, the price is $1,000 (par).
If market rates rise so that buyers demand 5 percent, the price falls to about $922.
If they fall to 3 percent, the price rises to about $1,086.
The longer the time to maturity, the larger the swing: at a 5 percent market yield, the same 4 percent bond with 30 years left would be worth about $845, but with two years left about $981. Someone who holds any of these bonds to maturity still receives every coupon and the $1,000 at the end; the price change matters to anyone who sells before then.
The Treasury publishes the yields on its securities every business day; on 6 November 2026 its par yield curve put the 10-year yield at 4.86 percent and the 30-year at 5.26 percent, against 4.02 percent for one month.
Borrowing by selling transferable debt is centuries old. One early survivor is held by Yale University: a bond issued on 15 May 1648 by the Hoogheemraadschap Lekdijk Bovendams, a Dutch water board, to pay for improvements to a local dike. It was a perpetual bond, one with no maturity date, for 1,000 Carolus guilders, originally paying 5 percent a year, later cut to 3.5 and then 2.5 percent. Yale acquired it in 2003, and in 2015 the water board's successor, Stichtse Rijnlanden, paid it 136.20 euros covering twelve years of interest.
War has repeatedly driven government borrowing. The Bank of England, which opened for business on 1 August 1694, began as a private bank to act as banker to the government and was primarily founded to fund the war effort against France; its early years were dominated by the government's demands for finance.
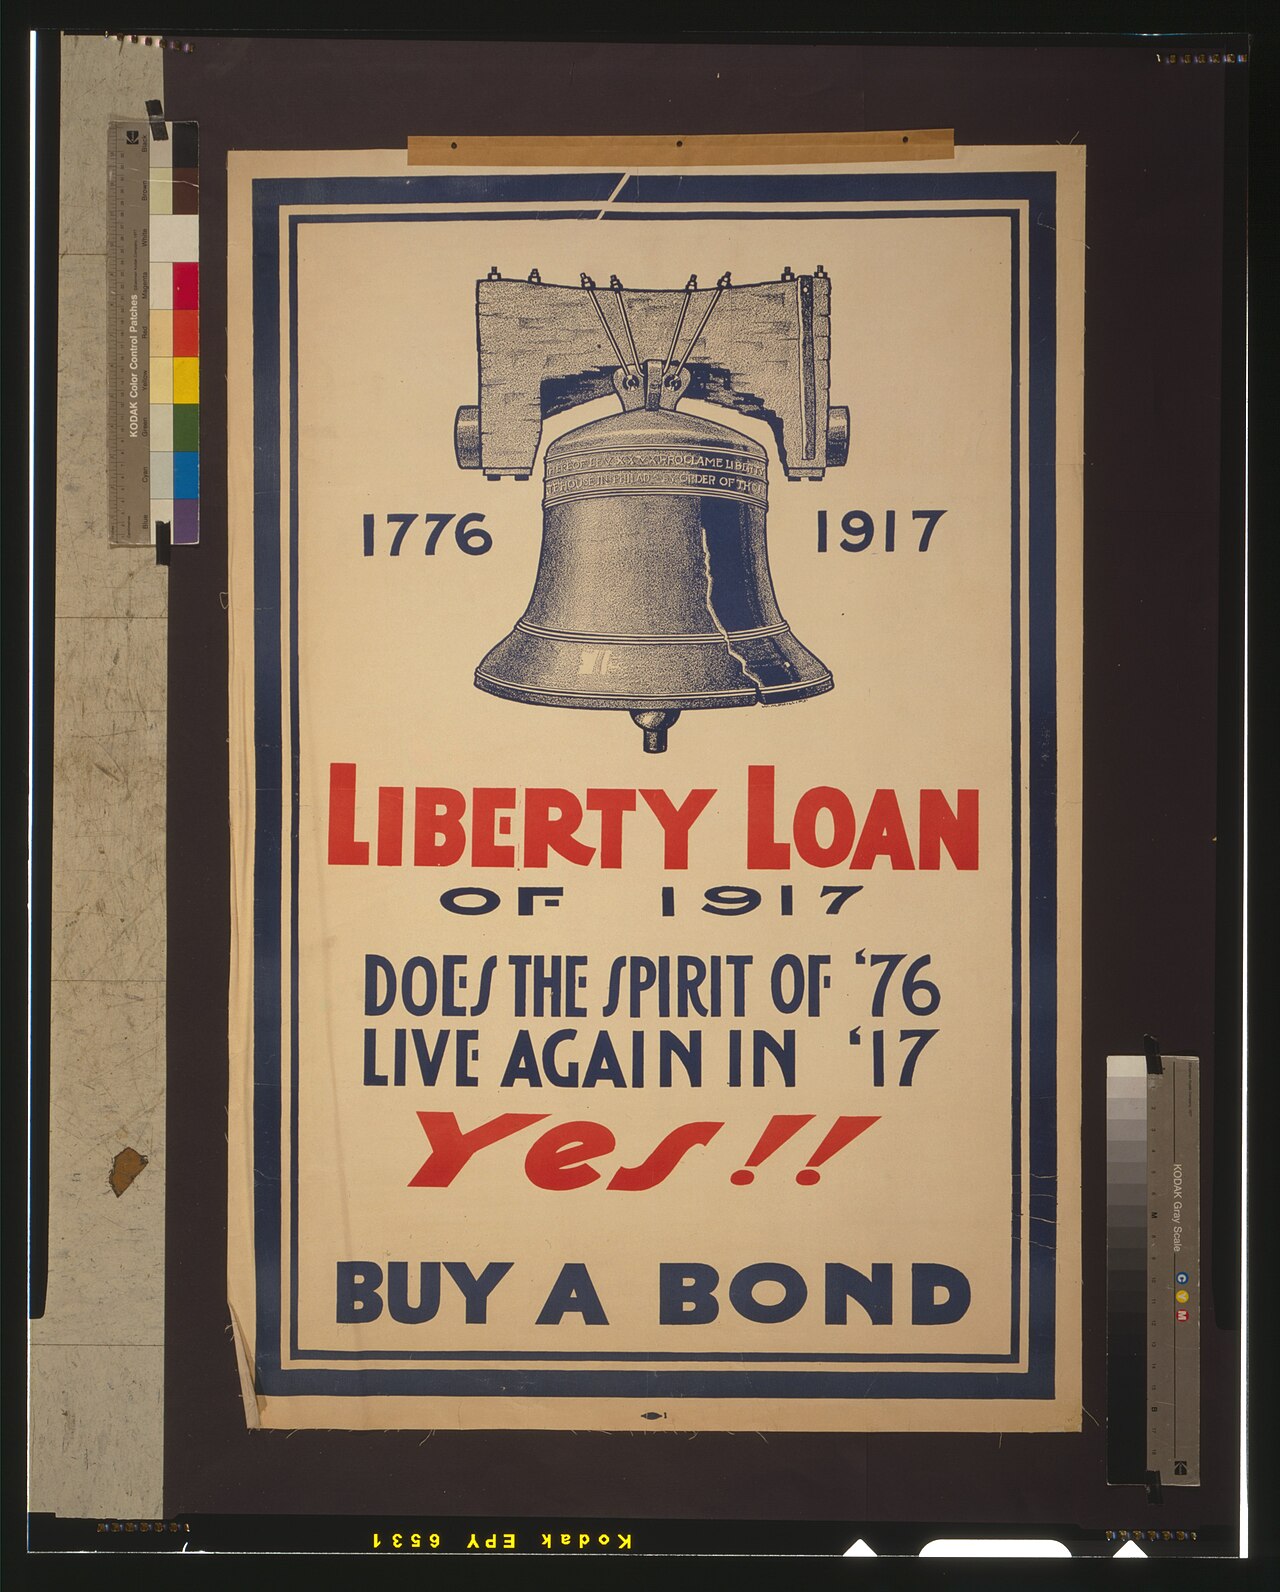
In the United States, the Treasury paid for the First World War largely by selling Liberty Bonds to the public. In a Federal Reserve History essay, Richard Sutch describes four Liberty Loan drives, the first announced on 28 April 1917, followed by a fifth "Victory Loan" after the armistice. The Federal Reserve and its member banks conducted the sales; more than $17 billion was raised through bonds, against $8.8 billion from taxes, so that almost exactly two-thirds of the war funds came from bonds. By the war's end, Sutch writes, twenty million individuals had bought them.
A First World War poster urging Americans to buy Liberty Bonds.
The bond market is far larger than most people picture. The Securities Industry and Financial Markets Association (SIFMA), an industry group, put U.S. fixed-income securities outstanding at $51.4 trillion as of the second quarter of 2026, up 7.0 percent from a year earlier, a figure that excludes mortgage-backed and asset-backed securities.
Bonds can be bought when they are first sold (the primary market) or traded afterwards (the secondary market). FINRA notes that corporate bonds mostly trade in the over-the-counter (OTC) market, and that it collects trade reports on many bonds through a system called TRACE. Treasury bonds can be bought directly from the government at auction or through a bank or broker. Many investors hold bonds indirectly through bond funds, mutual funds or exchange-traded funds that invest in bonds.
Micwyn auf deinen Home-BildschirmEigenes Symbol, Vollbild und Benachrichtigungen.
Micwyn hat eine neue Adresse: micwyn.comSchalte Benachrichtigungen hier wieder ein, damit sie weiter ankommen.Füge die neue Adresse zu deinem Home-Bildschirm hinzu.EinschaltenInstallieren
 Micwyn· EnzyklopädieAI
· 11 Min. Lesezeit · 0 Kommentare · 0 Aufrufe