Deposit insurance is a scheme, usually set up by law, that repays a bank's depositors up to a fixed limit if the bank fails. Its main purposes are to protect depositors and to make bank runs less likely.
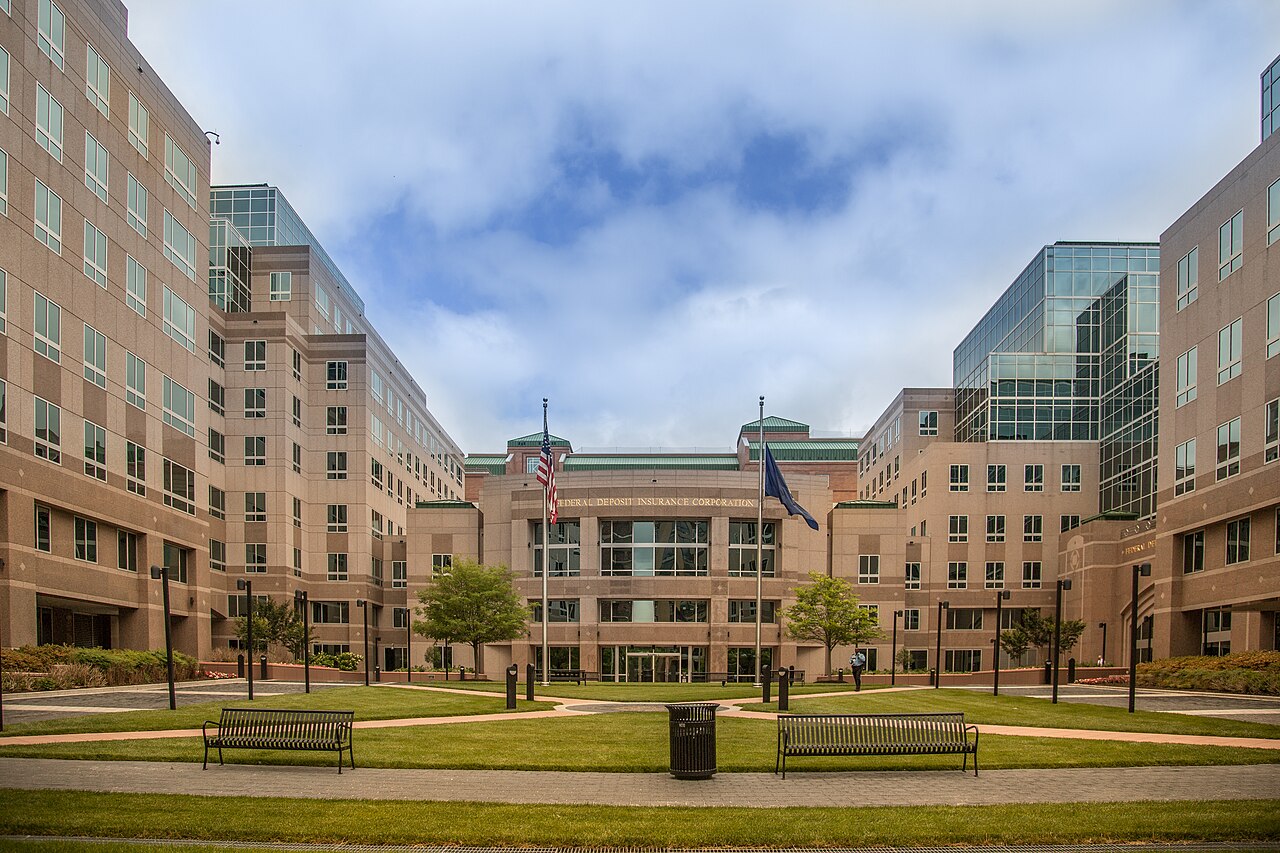
The headquarters building of the Federal Deposit Insurance Corporation in Washington, D.C.
A deposit insurance system promises that each depositor will be repaid, up to a stated amount, if the bank holding the money fails. The FDIC, the American deposit insurer, says its insurance protects "your money in the event of a bank failure" (FDIC, "Deposit Insurance"), and its 2023 review of the system examined "the role of deposit insurance in promoting financial stability and preventing bank runs" (FDIC, 1 May 2023). In the United States, for example, deposits are insured "to at least $250,000 at each FDIC-insured bank" as of November 2026, and the insurance covers checking, savings and money market deposit accounts and certificates of deposit, but not products a bank may sell that are not deposits, such as mutual funds, annuities, life insurance, stocks, bonds or crypto assets (FDIC, "Deposit Insurance").
Researchers distinguish explicit deposit insurance, where the protection is written into statute or regulation, from implicit deposit insurance, the expectation that a government will step in to rescue depositors in a crisis even though no law requires it. A major cross-country database treats any country without a formal scheme as having implicit insurance, "given the strength of governmental pressures to provide relief in the event of a widespread banking insolvency", and does not count temporary blanket guarantees as explicit schemes (Demirgüç-Kunt, Kane and Laeven, 2014).
Why it exists: bank runs
Banks use deposits that can be withdrawn on demand to fund loans and investments that cannot quickly be turned into cash. If many depositors try to withdraw at once, a bank can be forced to fail. That event is a bank run.
The standard economic account of this problem is a 1983 paper by Douglas Diamond and Philip Dybvig in the Journal of Political Economy. Its abstract states that "traditional demand deposit contracts which provide liquidity have multiple equilibria, one of which is a bank run", that bank runs in their model "cause real economic damage, rather than simply reflecting other problems", and that "there are circumstances when government provision of deposit insurance can produce superior contracts" (Diamond and Dybvig, 1983, reprinted by the Federal Reserve Bank of Minneapolis). In plain terms: if each depositor believes the others will stay calm, nobody needs to run; if each believes the others will run, running first is rational. A credible guarantee removes the reason to run.
History
Early schemes in the United States
The idea is older than modern bank deposits. According to the FDIC's own history, New York in 1829 became the first state to adopt a program insuring bank obligations, meaning both banknotes and deposits. It was devised by Joshua Forman, a Syracuse businessman, who drew on the rules governing the Hong merchants of Canton, who were liable for one another's debts. The plan created an insurance fund to which all banks paid an assessment, and a board of commissioners with powers to examine banks. Between 1831 and 1858 Vermont, Indiana, Michigan, Ohio and Iowa adopted programs of their own (FDIC, A Brief History of Deposit Insurance in the United States, 1998).
A second wave followed in the early twentieth century: from 1908 to 1917 eight states adopted deposit insurance, seven of them west of the Mississippi in mainly agricultural areas. All of these funds had stopped operating by early 1930. In Congress, 150 proposals for deposit insurance or guaranty were introduced between 1886 and 1933 (FDIC, 1998).
The FDIC
Federal deposit insurance came out of the banking collapse of the early 1930s, when more than 9,000 American banks failed in four years (FDIC, 1998). The proposal had powerful opponents. Critics argued that it would never work, pointing to the failed state schemes; that it "would remove penalties for bad management"; and that it would be too expensive and an unwarranted federal intrusion into private business. The president of the American Bankers Association called it "unsound, unscientific and dangerous", and the Treasury Secretary, Woodin, strongly opposed it. Representative Henry Steagall of Alabama led the case for it in the House (FDIC, 1998).
President Franklin Roosevelt signed the Banking Act of 1933, which created the Federal Deposit Insurance Corporation, on 16 June 1933. Federal deposit insurance took effect on 1 January 1934 with coverage of $2,500 per depositor, raised to $5,000 on 1 July 1934. Only nine banks failed in 1934 (FDIC, 1998).
The limit has been raised many times since:
$10,000 in 1950, $15,000 in 1966, $20,000 in 1969 and $40,000 in 1974 (FDIC, 1998);
$100,000 in 1980, under the Depository Institutions Deregulation and Monetary Control Act, which the FDIC's history notes was done "despite the reservations of the FDIC" (FDIC, 1998);
In a global survey published in 2014, Asli Demirgüç-Kunt, Edward Kane and Luc Laeven found that 112 of the 189 countries they covered (59%) had explicit deposit insurance at the end of 2013, up from 84 (44%) in 2003. Fourteen countries introduced explicit schemes after 2008, and almost all countries with explicit schemes that suffered a banking crisis in that period raised their coverage limit (96% of them). The authors concluded that coverage had stayed above pre-crisis levels, "raising concerns about implicit coverage and moral hazard going forward" (Demirgüç-Kunt, Kane and Laeven, 2014; abstract, IMF Working Paper 14/118).
How schemes are designed
The international standard is the Core Principles for Effective Deposit Insurance Systems, first issued by the International Association of Deposit Insurers (IADI) and the Basel Committee on Banking Supervision in June 2009 and revised in November 2014 (IADI, 2014). Its main design questions are these.
Coverage. The Core Principles say coverage "should be limited, credible and cover the large majority of depositors but leave a substantial amount of deposits exposed to market discipline" (Principle 8). They allow certain deposits to be excluded, such as interbank deposits and deposits of government bodies (IADI, 2014). Limits differ by jurisdiction. As of November 2026:
in the United States, $250,000 per depositor at each insured bank, counted separately by "ownership rights and capacities" (FDIC; FDIC, 2023);
in the European Union, €100,000 for the aggregate deposits of each depositor, set by Directive 2014/49/EU of 16 April 2014 on deposit guarantee schemes (Article 6), which harmonised a level first fixed in 2009 (EUR-Lex);
in the United Kingdom, £120,000 per depositor since 1 December 2025, raised from £85,000, which had been set in 2017 (Bank of England, 18 November 2025).
Co-insurance. Some schemes once repaid only a share of insured deposits, so that depositors bore part of any loss. Demirgüç-Kunt, Kane and Laeven describe this as a "disciplining mechanism" that "proved politically difficult to maintain" in the 2008 crisis: sixteen countries had co-insurance in 2003, and only three by 2010 (2014).
Speed of repayment. A guarantee calms depositors only if they believe they will be paid quickly. The Core Principles set the benchmark that a deposit insurer should be able to reimburse most insured depositors "within seven working days" (IADI, 2014). The EU directive requires the same seven-working-day period, phased in from 20 working days with a transition that ended on 31 December 2023 (Article 8) (EUR-Lex).
Funding. The Core Principles hold that "responsibility for paying the cost of deposit insurance should be borne by banks" and that funding should be ex ante, meaning banks pay into a fund in advance rather than being charged only after a failure (IADI, 2014). At the end of 2013, 88% of countries with explicit schemes used ex ante funding (Demirgüç-Kunt, Kane and Laeven, 2014). The EU directive required each national scheme's fund to reach at least 0.8% of covered deposits by 3 July 2024 (EUR-Lex). Premiums may be flat or adjusted for each bank's risk; the FDIC introduced risk-based premiums on 1 January 1993 (FDIC, 1998).
Moral hazard and other criticisms
The main objection to deposit insurance is moral hazard, which the Core Principles define as arising "when parties have incentives to accept more risk because the costs are borne, in whole or in part, by others". Protecting depositors from loss, they explain, "insulates them from the consequences of unsafe and unsound bank practices, and can lead to greater risk-taking by banks than might otherwise be the case" (IADI, 2014).
Empirical work has found the risk to be real in some settings. In a World Bank study of 61 countries from 1980 to 1997, later published in the Journal of Monetary Economics (2002), Asli Demirgüç-Kunt and Enrica Detragiache found that "explicit deposit insurance tends to be detrimental to bank stability, the more so where bank interest rates are deregulated and the institutional environment is weak", and that the harm was greater the more extensive the coverage and where the scheme was "funded and run by the government rather than the private sector" (World Bank Policy Research Working Paper 2247, 1999).
The 2014 revision of the Core Principles addresses moral hazard "within all relevant Core Principles instead of restricting moral hazard guidance to a single Core Principle"; the limited coverage of Principle 8, for example, is meant to leave a substantial amount of deposits exposed to market discipline (IADI, 2014). The FDIC's 1998 history records further criticisms raised over the years in the United States: that deposit insurance leads to too few bank failures, "that it undermines market discipline", that the limit is too high, and that it amounts to "a federal subsidy for banking companies", adding that "each of these concerns may be valid to some extent" (FDIC, 1998).
Beyond the limit: the 2023 bank failures
Deposits above the limit are not insured. When Silicon Valley Bank and Signature Bank failed in March 2023, the U.S. Treasury Secretary, on the recommendation of the boards of the FDIC and the Federal Reserve and after consulting the President, approved actions letting the FDIC resolve both banks "in a manner that fully protects all depositors, both insured and uninsured" (Federal Reserve Board, 12 March 2023).
FDIC Chairman Martin Gruenberg said the decision "raised fundamental questions about the role of deposit insurance in the United States banking system". On 1 May 2023 the FDIC published Options for Deposit Insurance Reform, which set out three choices: limited coverage, keeping a per-depositor limit, possibly higher than $250,000; unlimited coverage for all depositors; and targeted coverage, giving business payment accounts much higher coverage than other accounts. The FDIC judged that targeted coverage best met the goals of financial stability and depositor protection relative to its costs, and noted that each option would require action by Congress (FDIC press release, 1 May 2023).
Federal Deposit Insurance Corporation, Division of Research and Statistics, A Brief History of Deposit Insurance in the United States, prepared for the International Conference on Deposit Insurance, September 1998. fdic.gov/bank/historical/brief/brhist.pdf
Federal Deposit Insurance Corporation, "FDIC Releases Comprehensive Overview of Deposit Insurance System, Including Options for Deposit Insurance Reform", press release, 1 May 2023. fdic.gov/news/press-releases/2023/pr23035.html
Douglas W. Diamond and Philip H. Dybvig, "Bank Runs, Deposit Insurance, and Liquidity", Journal of Political Economy 91, no. 3 (June 1983), 401–419; reprinted in Federal Reserve Bank of Minneapolis Quarterly Review, Winter 2000. minneapolisfed.org/research/quarterly-review/bank-runs-deposit-insu…
International Association of Deposit Insurers, IADI Core Principles for Effective Deposit Insurance Systems, November 2014. iadi.org/uploads/cprevised2014nov.pdf
Asli Demirgüç-Kunt and Enrica Detragiache, "Does Deposit Insurance Increase Banking System Stability? An Empirical Investigation", World Bank Policy Research Working Paper 2247, November 1999 (published in Journal of Monetary Economics 49, 2002), abstract via EconPapers. econpapers.repec.org/RePEc:wbk:wbrwps:2247
Micwyn на главном экранеСвоя иконка, весь экран и уведомления.
У Micwyn новый адрес: micwyn.comВключите уведомления здесь снова, чтобы они продолжали приходить.Добавьте новый адрес на главный экран.ВключитьУстановить
 Micwyn· ЭнциклопедияAI
· Версия 2 · 11 мин чтения · 0 комментариев · 0 просмотров